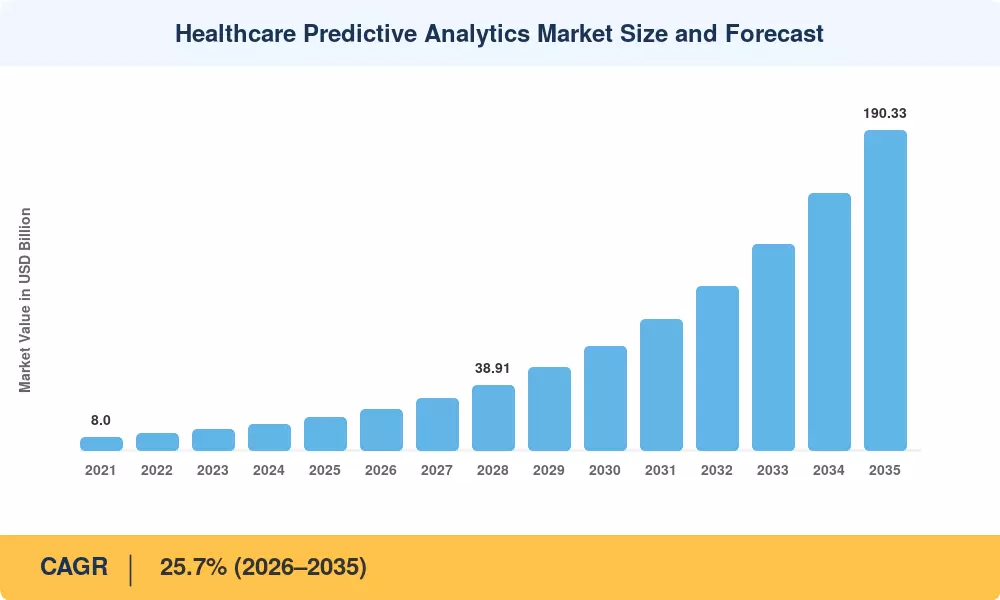
Healthcare Predictive Analytics Market to Surge from USD 19.35 Bn in 2025 to USD 190.33 Bn by 2035- Value-Based Care Expansion, Mandated Interoperability
NY, CA, UNITED STATES, September 22, 2026 /EINPresswire.com/ — As per Market Research Future, the global Healthcare Predictive Analytics Market size is projected to reach USD 190.33 Billion by 2035 from USD 19.35 Billion in 2025, at a CAGR of 25.7% during the forecast period 2026–2035. The market entered the forecast window at USD 24.32 Billion in 2026.
The 25.7% CAGR—anchored by structural shifts in healthcare payment and data policy—is propelled by three converging forces: the global expansion of value-based reimbursement, with CMS committed to placing all traditional Medicare beneficiaries in an accountable care relationship by 2030 and roughly 34 million Medicare Advantage beneficiaries making accurate risk scoring a direct determinant of plan revenue; advancements in analytics technology, particularly foundation models applied to unstructured clinical text and streaming architectures that score patients continuously against live EHR feeds, which significantly improve deterioration detection and coding accuracy; and mandated interoperability, including 21st Century Cures Act information-blocking enforcement and the EU’s European Health Data Space regulation, that unlocks the underlying data on which predictive models depend.
Global health technology companies and government health bodies are amplifying this momentum. Optum maintains its position as a scale incumbent with captive payer demand, while Oracle Health leverages its installed EHR base to embed predictive capability as a platform feature. CMS shared-savings participants returned USD 2.4 billion in net savings in the most recent performance year, with about 13.7 million Medicare beneficiaries enrolled in accountable care agreements. According to WHO projections, a global shortfall of roughly 10 million health workers by 2030 is forcing understaffed units toward automated triage. These forces are creating the data infrastructure and purchaser demand on which the Healthcare Predictive Analytics Market depends.
Request A Free Sample:
https://www.marketresearchfuture.com/sample_request/7549
Key Market Trends & Growth Drivers
Risk-Bearing Contracts Turn Forecasts Into Revenue
The market is witnessing a decisive shift of provider revenue toward risk. As value-based contracts expand globally, more healthcare organizations are purchasing scoring engines that identify rising-risk members 60 to 90 days in advance. This trend indicates a shift in buyer economics from retrospective reporting to predictive margin protection, with predictive analytics platforms being recognized for their direct impact on shared-savings performance. Optum continues advancing risk stratification and payer analytics suites through sustained platform innovation.
Advancements in AI and Foundation Models
Innovations in analytics technology are becoming a hallmark of the industry. Vendors are applying transformer architectures to the unstructured 80% of clinically decisive data—progress notes, discharge summaries, and radiology narratives—that earlier models never reached. These advancements aim to enhance prediction quality and coding accuracy, potentially leading to better patient outcomes and increased market penetration. Predictive analytics workloads commanded approximately 41.6% of market revenue in 2025, while prescriptive analytics—the fastest-growing type at 29.8% CAGR—increasingly determines contract renewals.
Integration of Interoperability and Streaming Data Architectures
The incorporation of mandated interoperability into the industry is gaining traction. Standardized FHIR endpoints required of certified EHRs, information-blocking enforcement, and the European Health Data Space—which entered into force in 2025—have turned longitudinal record assembly from a custom integration project into a configuration exercise. Oracle Health continues investing in EHR-embedded analytics and cloud data platforms, having launched a next-generation EHR with embedded generative AI in September 2024.
Increasing Prevalence of Chronic Disease and Workforce Shortages
Rising chronic disease burden and clinician staffing gaps are primary drivers. Understaffed units cannot manually review every chart, and automated surveillance that ranks the top 5% of patients by deterioration probability is increasingly framed as a labour-substitution purchase. The market is projected to expand as health systems deploy predictive triage to absorb workforce constraints. Japan’s demographic profile—over 29% of the population aged 65 and above—and ageing populations across Europe, China, and North America underscore the urgent need for scalable analytics solutions.
Ask for Customization:
https://www.marketresearchfuture.com/ask_for_customize/7549
Market Segment Insights
BY ANALYTICS TYPE
Predictive Analytics: Largest segment with 41.6% share in 2025, driven by risk stratification and forecasting demand. Optum continues expanding predictive payer analytics suites through its captive payer relationships.
Prescriptive Analytics: Fastest-growing segment at 29.8% CAGR, as buyers increasingly pay for recommended actions and expected effect sizes rather than predictions alone.
Descriptive Analytics: 27.4% share in 2025, anchored by regulatory and quality reporting baselines.
Other Types: Positioned as a novel entry, catering to simulation and digital twin pilots.
BY APPLICATION
Clinical Data Analytics: Largest segment, generating about USD 7.94 billion in 2025, due to deterioration and readmission prevention demand. Oracle Health continues strengthening clinical analytics embedded within its EHR platform.
Population Health Analytics: Fastest-growing application at close to 28.4% CAGR, as risk-bearing entities scale attribution models.
Financial Data Analytics: 21.3% share of application revenue, driven by denials management and cost forecasting.
Operational & Administrative Analytics: Expanding at 26.9% CAGR, with bed-management and OR-scheduling models producing provable savings within a single fiscal quarter.
BY COMPONENT
Software: Largest segment with 58.3% share in 2025, driven by platform licensing and model libraries.
Services: USD 6.71 billion in 2025 revenue, consistently outperforming expectations as data remediation proves to be the real workload—underestimated by a factor of two to three in most procurement cycles.
Hardware: 6.4% share, supporting on-premise inference infrastructure in sovereignty-sensitive deployments.
BY MODE OF DELIVERY
On-Premise: Dominant mode with 38.2% share in 2025, preferred in European public systems and Gulf sovereign deployments where residency requirements override cost logic.
Cloud-Based: Fastest-growing mode at 30.9% CAGR, positioning itself as an appealing alternative through elastic compute and faster upgrades. Microsoft continues strengthening its Azure health data services and AI enablement layer.
Web-Hosted: USD 2.24 billion in 2025, offering mid-market affordability.
Read Detailed Insights:
https://www.marketresearchfuture.com/reports/healthcare-predictive-analytics-market-7549
Regional Outlook
North America — Market Leader in Value-Based Care
North America leads with 44.8% of global revenue in 2025, generating around USD 8.67 Billion. The region’s growth is driven by mature value-based contracting, Medicare Advantage risk adjustment, and accountable care scale, with the United States holding 88.4% of the regional market. Roughly 34 million Medicare Advantage beneficiaries make accurate risk scoring a direct determinant of plan revenue, and CMS audit expansion has pushed payers toward defensible, explainable model pipelines. The competitive landscape is characterized by continuous innovation and platform consolidation among leading health technology companies.
Europe — Second Largest Market
Europe was valued at USD 4.76 Billion in 2025, representing the second-largest regional market, driven by statutory payer mandates and EHDS compliance. The UK’s NHS federated data platform rollout—advanced to additional trusts in April 2025—created one of the largest single-payer analytics deployments in Europe, while Germany’s statutory sickness fund analytics obligations anchor continental demand. Leading countries include Germany, the UK, and France, where vendors with GDPR-native architectures and documented lawful bases close deals. Nordic population registries offer decades of linked longitudinal records unmatched worldwide.
Asia-Pacific — Fastest-Growing Market Segment
The Asia-Pacific region is the fastest-growing market, compounding at approximately a 30.2% CAGR. Growth is propelled by national digital health missions, with India’s Ayushman Bharat Digital Mission issuing over 700 million health account IDs and posting a 33.6% CAGR, and China’s tertiary hospital grading standards tying analytics maturity to licensing. Japan’s ageing population—over 29% aged 65 and above—drives demand toward long-term care resource forecasting. ASEAN markets benefit from private hospital group expansion and cloud-first builds.
Middle East & Africa and South America — Emerging Potential
The Middle East & Africa region contributes approximately USD 0.70 Billion in 2025, driven by sovereign transformation programmes such as Saudi Arabia’s Health Sector Transformation Program, which awarded multi-year national health data platform contracts in February 2025. South America holds around 4.1% of the global share, led by Brazil, where ANS-regulated private operators face escalating medical-loss ratios that make cost prediction existential rather than aspirational.
Competitive Landscape and Recent Developments
The Healthcare Predictive Analytics Market is characterized by moderate fragmentation and rapid consolidation, driven by the global shift toward risk-bearing care models. The top five vendors hold an estimated 38–43% of global revenue, enough to shape standards but not enough to dictate pricing, with buyers increasingly collapsing eleven or twelve vendor stacks down to two or three platforms.
KEY COMPANIES AND RECENT MILESTONES
Optum (US): Market leader with an estimated 11–14% revenue share. Offers risk stratification and payer analytics suites, uniquely positioned with captive payer demand from UnitedHealth Group.
Oracle Health (US) (September 2024): Launched a next-generation EHR with embedded generative AI and analytics, signalling that predictive capability is becoming a platform feature rather than an add-on purchase. Holds an estimated 8–11% revenue share.
Health Catalyst (US) (May 2024): Acquired complementary analytics assets to broaden ambulatory coverage, continuing mid-market consolidation. Holds an estimated 3–5% revenue share with its provider-native data operating system.
IQVIA (US) (July 2025): Expanded real-world evidence partnerships with health systems under revenue-share licensing terms, validating provider-side data monetization models.
Other Key Players: Merative (US), SAS Institute (US), Inovalon (US), Microsoft (US), Veradigm (US), Cotiviti (US), MedeAnalytics (US), Google Cloud (US).
Regulatory Milestones: CMS finalized expanded risk-adjustment data validation audits across all Medicare Advantage contracts (November 2024); the European Health Data Space entered into force (March 2025); and the FDA issued final guidance on predetermined change control plans for AI-enabled device software (December 2024).
Future Outlook: 2026–2035
The Healthcare Predictive Analytics Market is projected to reach USD 190.33 billion by 2035, growing at a CAGR of 25.7%, driven by value-based reimbursement expansion, mandated interoperability, and AI-driven clinical insight.
New opportunities lie in:
– Expansion into emerging markets with cloud-native leapfrog deployments
– Development of closed-loop autonomous workflows and prescriptive intervention engines
– Investment in model governance-as-a-service and payer-provider data monetization models
By 2035, the Healthcare Predictive Analytics Market is expected to achieve substantial growth and innovation, with the next decade rewarding vendors who prove outcomes rather than deliver dashboards.
Related Reports:
https://www.marketresearchfuture.com/ja/reports/pharmerging-market-29204
https://www.marketresearchfuture.com/de/reports/pharmerging-market-29204
https://www.marketresearchfuture.com/es/reports/pharmerging-market-29204
https://www.marketresearchfuture.com/zh-cn/reports/pharmerging-market-29204
https://www.marketresearchfuture.com/ko/reports/pharmerging-market-29204
https://www.marketresearchfuture.com/fr/reports/pharmacovigilance-market-8451
https://www.marketresearchfuture.com/ja/reports/pharmacovigilance-market-8451
https://www.marketresearchfuture.com/de/reports/pharmacovigilance-market-8451
https://www.marketresearchfuture.com/es/reports/pharmacovigilance-market-8451
https://www.marketresearchfuture.com/zh-cn/reports/pharmacovigilance-market-8451
https://www.marketresearchfuture.com/ko/reports/pharmacovigilance-market-8451
https://www.marketresearchfuture.com/fr/reports/orphan-drugs-market-2312
https://www.marketresearchfuture.com/ja/reports/orphan-drugs-market-2312
https://www.marketresearchfuture.com/de/reports/orphan-drugs-market-2312
https://www.marketresearchfuture.com/fr/reports/organ-on-chip-market-8498
Market Research Future
Market Research Future
+1 855-661-4441
email us here
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery